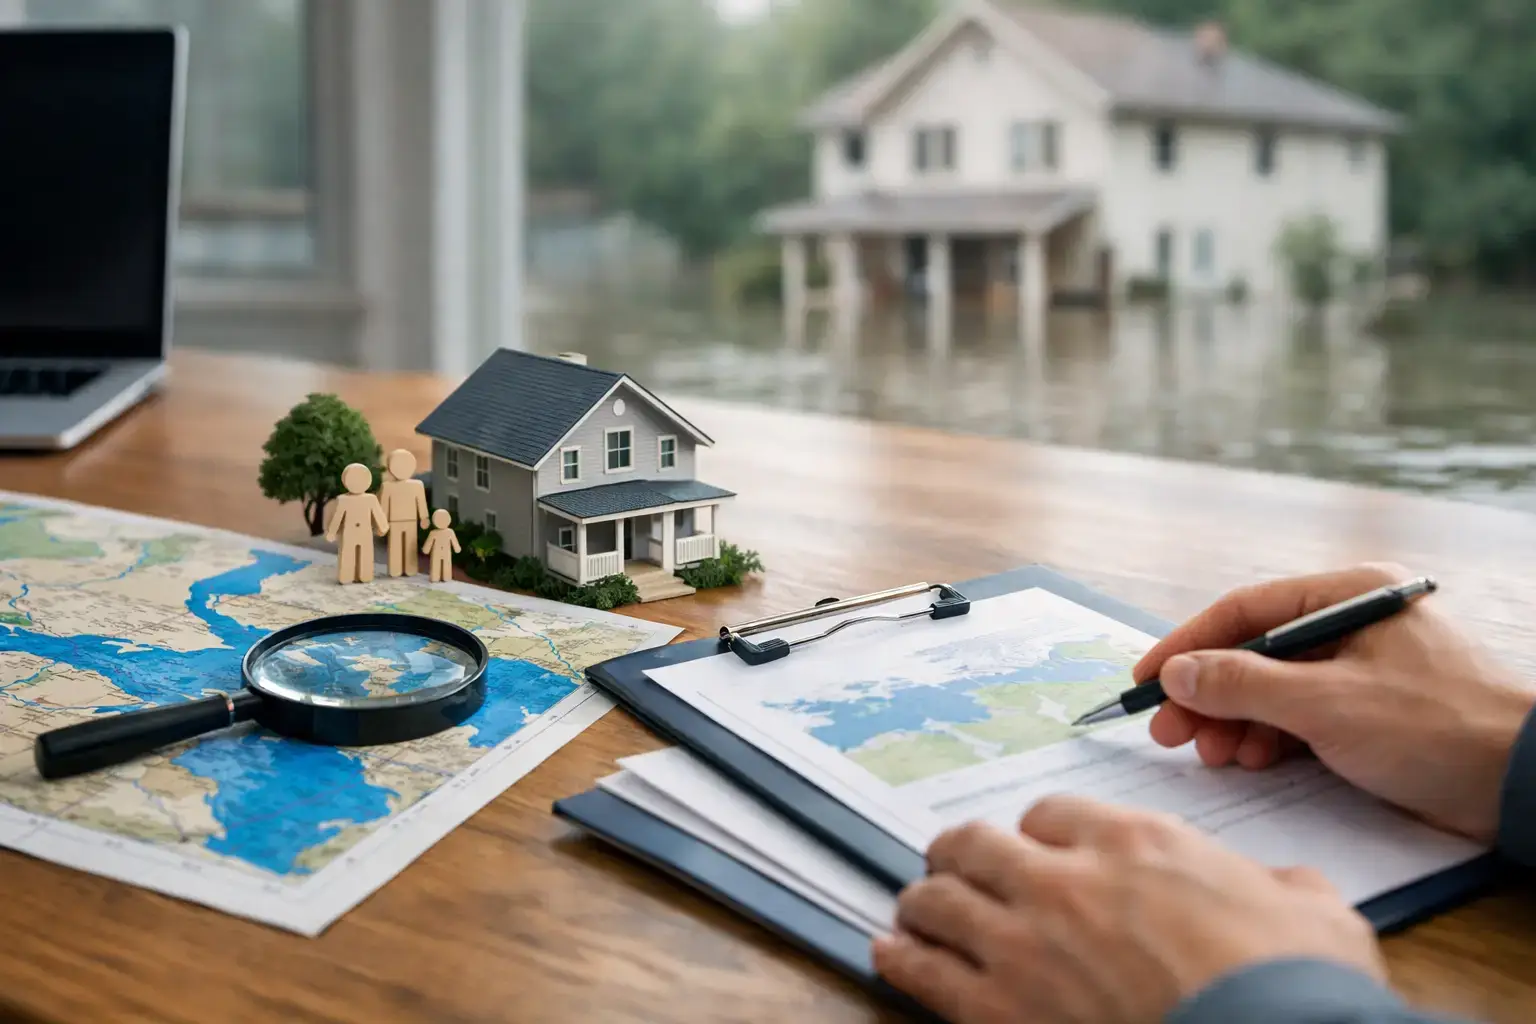
A home can look perfect on a sunny afternoon and still carry flood considerations that deserve a closer look. In coastal Pinellas County, evaluating flood zones is not about automatically ruling out a property. It is about understanding the property’s actual exposure, likely insurance costs, lending requirements, and how those factors may affect your comfort and resale options.
However, For many buyers, especially those drawn to Dunedin waterfront homes or neighborhoods near the Intracoastal, flood-zone researchshould begin before an offer is written. The right home may still be a strong purchase in a higher-risk zone, but the decision should be based on clear facts rather than assumptions.
What a Flood Zone Does – and Does Not – Tell You
Also, Flood zones are map-based designations used to identify areas with differing levels of flood risk. FEMA flood maps are the starting point most buyers see, and they matter because lenders generally require flood insurance for homes with federally backed mortgages located in certain higher-risk zones.
The designation alone does not tell the full story. Two homes on the same street may have different elevations, construction types, drainage conditions, and flood-insurance histories. One may sit several feet higher than another. One may have a raised living area, while another has finished space at ground level. Those differences can significantly affect risk and cost.
Also, A property outside a high-risk flood zone is not flood-proof, either. Heavy rainfall, storm surge, drainage failures, and changing weather patterns do not always follow map boundaries. Conversely, a property in a designated flood zone may have a long history of avoiding water intrusion because it is well elevated and carefully maintained.
In addition, The goal is not to treat a map as a verdict. It is to use it as the first layer of due diligence.
Evaluating Flood Zones Starts With the Exact Property
Online map tools can provide a useful early view, but buyers should verify the designation for the specific parcel. A listing description that says “not in a flood zone” can be incomplete or outdated, and a nearby property’s designation is not a substitute for checking the home under consideration.
For example, Pay attention to whether the property is in a Special Flood Hazard Area, often associated with zones such as AE, VE, or A. These areas typically carry mandatory flood-insurancerequirements when financing is involved. Coastal V zones can require additional scrutiny because they may be exposed to wave action during coastal storms.
Also ask whether the map has changed over time. FEMA map updates can alter a property’s designation, which may affect insurance requirements and buyer perception. A home that was once outside a higher-risk area may now be included, or the reverse may be true. Understanding when the current designation took effect gives helpful context.
Elevation Often Matters More Than Buyers Expect
Also, The elevation of the structure is one of the most meaningful details in a flood-risk review. Specifically, buyers should compare the lowest finished floor with the property’s Base Flood Elevation, or BFE. The BFE is the estimated elevation floodwater could reach during a base flood event.
When the living area is above BFE, insurance pricing may be more favorable than it is for a similar home below that elevation. An elevation certificate, when available, can provide the measurements insurers need to evaluate a policy accurately. It may also identify features such as flood vents, enclosures, or machinery located below the living area.
Do not assume a high first floor means every part of the property is protected. Garages, storage rooms, ground-level enclosures, pool equipment, HVAC systems, and electrical components can all be vulnerable. Those areas may be less expensive to repair than living space, but their condition still matters after a storm.
Get Insurance Numbers Before You Commit
Also, Flood insurance should be researched early, ideally before the inspection period ends. Premiums can vary widely based on the home’s flood zone, elevation, replacement cost, prior coverage, mitigation features, and insurer pricing. A general estimate from a friend or neighbor is not enough to support a purchase decision.
In addition, Request insurance quotes for the actual property and ask what coverage is included, what is excluded, and what deductible applies. Standard homeowners insurance usually does not cover flood damage. Buyers sometimes discover this after assuming their regular policy would handle water damage from a storm surge or rising water event.
It is also wise to ask whether the current owner has an existing flood policy and whether it may be transferable. That does not guarantee the buyer will receive the same premium, but it can provide useful information about prior coverage and claims. Your lender and insurance professional can clarify what is required for your loan and what additional coverage may be prudent.
However, Insurance is not just a monthly expense. It is part of the home’s ongoing ownership cost, alongside property taxes, HOA fees, maintenance, and wind coverage. A property that fits the purchase budget but strains the long-term monthly budget may not be the right fit.
Ask Better Questions About Flood History
Also, Seller disclosures and direct questions can reveal details a map cannot. Ask whether water has entered the home, garage, or enclosed lower level; whether the property has received insurance claims; and whether the seller has completed flood-related repairs or improvements.
It is reasonable to ask about the source of any water intrusion. Was it storm surge, roof failure, wind-driven rain, a drainage issue, a plumbing leak, or something else? The answer matters because the solution, risk profile, and potential insurance coverage can be very different.
Also, For homes near the coast, also ask about the age and condition of major systems. Electrical panels, HVAC equipment, water heaters, pool equipment, and irrigation controls can be costly to replace if damaged by saltwater or floodwater. Permits for substantial renovations, additions, or post-storm repairs may offer useful context about how the property has been maintained.
However, A thorough home inspection remains essential, but buyers should understand its limits. A general inspector can identify visible signs of moisture, deterioration, drainage concerns, and questionable repairs. For a home with specific flood concerns, additional input from an insurance professional, contractor, engineer, or elevation specialist may be worthwhile.
Look Beyond the House at the Surrounding Area
A property’s location within its neighborhood can be as important as its FEMA designation. During a showing, look at the street elevation, nearby drainage inlets, swales, retention areas, and the route water would likely take during heavy rain. Notice whether driveways slope toward garages and whether neighboring homes appear to sit materially higher or lower.
Local knowledge is valuable here. In Dunedin, a few blocks can separate a more sheltered inland setting from a coastal location with different storm-surge and wind considerations. Proximity to water is a lifestyle benefit for many buyers, but it should come with a realistic understanding of maintenance, insurance, evacuation planning, and future market expectations.
Talk with neighbors when appropriate. They may share how the street performed during past storms, whether access was affected, or whether drainage improvements have been completed. Their perspective is not a replacement for professional due diligence, but it can help you form better questions.
Consider Resale Before You Buy
Flood-zone status can influence the future buyer pool, financing process, insurance affordability, and time on market. That does not mean homes in higher-risk areas are difficult to sell. Many are highly desirable because of their views, location, construction quality, and waterfront lifestyle. It does mean that future buyers will likely ask the same questions you are asking now.
A well-documented property can be easier to position at resale. Keep records of elevation certificates, insurance policies, mitigation work, drainage improvements, permits, inspections, and any repairs completed after a storm. If the home has performed well through severe weather, factual documentation can be more persuasive than a simple verbal assurance.
The right purchase strategy depends on the property. A newer elevated home with favorable insurance costs may justify a different offer and ownership plan than an older low-lying home that needs significant mitigation. Price, condition, location, and flood exposure should be considered together rather than in isolation.
Make the Decision With Clear Information
Flood-zone review should be part of a larger buying strategy, not a reason to panic or rush. A careful buyer verifies the map designation, reviews elevation, obtains real insurance quotes, studies disclosures, inspects the property closely, and considers long-term costs before moving forward.
If a home still fits your goals after that review, you can move ahead with greater confidence. And if the numbers or risks do not feel right, walking away early may protect both your budget and your peace of mind. The best home is not simply the one with the best view or the most attractive features – it is the one whose full ownership picture makes sense for you.